
 Polski
 English
GreenBottle is a Polish company from Białystok that has been creating innovative IT solutions and self-service...
Read more
Most viewed
Most viewed

DIBAL PS-50
PLN 695.00
Regular price
PLN 947.10

DIBAL G-305
PLN 995.00
Regular price
PLN 1,414.50
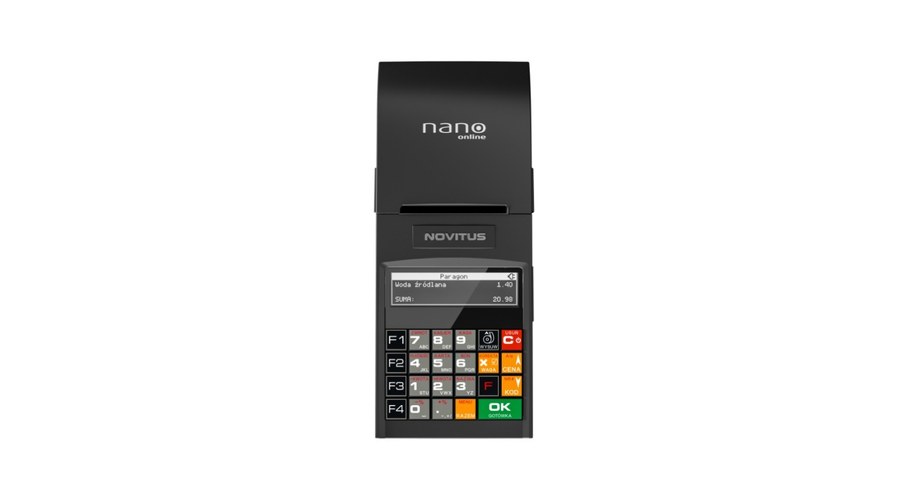
Reimbursement for the Purchase of an Online Fiscal Cash Register
Tax Relief for the Purchase of an Online Fiscal Cash Register
How to handle this matter?
You can handle this matter:
- in person at the tax office
- by mail
What should you know and who can use this service?
The relief for purchasing a cash register amounts to 90% of its net price (excl. VAT), but no more than PLN 700.
If you bought more than one online cash register, you can use the relief for each one, provided that you start using each of these cash registers at each point of sale no later than 6 months from the date you began recording sales.
You can apply for a refund if:
- your business became subject to the obligation to record sales on a fiscal cash register and you began keeping these records on an online cash register,
- your business is not obliged to record sales and you had not used a fiscal cash register at all until now, but you decided to keep such records on an online cash register.
This means that if, on Tuesday, 9 July 2019, you started recording sales on a different type of cash register (e.g. one with an electronic copy), and you bought your online cash register on Wednesday, 10 July 2019, you will not receive the relief.
The relief for purchasing an online cash register is available both to businesses that settle VAT (active VAT payers), and to businesses that are exempt from this obligation or perform only activities not subject to taxation and record sales on a fiscal cash register (non-active VAT payers).
Depending on your VAT payer status, you will settle the refund in your VAT return (active VAT payers) or by submitting an application to the tax office (Urząd Skarbowy) (non-active VAT payers).
Where can you handle this matter?
You can use this service at:
- the tax office (Urząd Skarbowy),
- the tax office for the largest entities.
What to do step by step?
-
If you are an active VAT payer – settle the refund in your VAT-7 or VAT-7K return
Businesses that settle on a monthly basis should settle the refund in the VAT-7 return. Businesses that settle quarterly should use the VAT-7K return.
How much you can settle depends on whether the amount you spent on purchasing the cash register, which you report in your settlement, is:
- lower than or equal to the amount of tax you must pay to the tax office for the given settlement period – in this case you can settle the relief in a single return, reducing the tax amount by the refund you are entitled to for purchasing the cash register,
- higher than the amount of tax you must pay to the tax office for the given settlement period – in this case you can reduce the tax amount by the relief you are entitled to. You can receive the remaining amount to your bank account (or credit union / SKOK account) or settle it in a subsequent VAT return.
Deadline
You can settle the refund in the VAT return for the period in which you started using the online cash register, or in any return for a later period – the right to the refund has no time limit (it does not expire).
If, in the period in which you started using the online cash register, you are not required to pay VAT, you can request that the relief you are entitled to for purchasing the cash register be refunded to your bank account or SKOK account, or you can settle the relief in a subsequent tax return.
-
If you are a non-active VAT payer – submit an application for reimbursement of the cost of purchasing the cash register
You submit the application to the head of the tax office (naczelnik urzędu skarbowego) that registered your cash register.
The application must include: first and last name (or company name), address, NIP (Tax Identification Number), and bank account number.
Remember to attach to the application:
- a copy of the invoice for the purchase of the fiscal cash register,
- a copy of proof of full payment for the cash register,
- a copy of the monthly fiscal report you issued on the cash register – as confirmation that you are keeping sales records.
You can print the application and deliver it in person, or send it to the office.
If you run a taxi business, additionally include in the application:
- your license number for operating road transport by taxi
- the registration number and side number of the taxi in which the online
fiscal cash register is registered - a copy of the certificate of re-verification (re-legalization) of the taximeter cooperating with the
special-purpose cash register.
Appointing a proxy
PLN 17 – stamp duty for a special power of attorney PPS-1 (optional)
If you act through a proxy, you must pay a fee for the power of attorney. You will not pay for a power of attorney granted to a husband, wife, children, parents, grandparents, grandchildren or siblings.
Fee: pay it to the account of the city or municipal office (urząd miasta or gminy) competent for the seat of the office where you are submitting the power of attorney (you can find the account number on the city or municipal office's website).
Example: if you submit the power of attorney to the Tax Office (Urząd Skarbowy) in Poznań, pay the fee to the account of the Poznań City Office (Urząd Miasta Poznania).
PLN 0 – fee for a general power of attorney PPO-1
You can appoint a general proxy for all tax matters (a natural person with full legal capacity – they do not have to be an advocate, legal counsel, or tax advisor). You can do this online via the Tax Portal (Portal Podatkowy). Submitting a general power of attorney PPO-1 is free of charge.
Note! You do not need to attach a copy of the general power of attorney – the tax office will check its scope itself in the Central Register of General Powers of Attorney (CRPO).
Important: if you appoint a general proxy, you do not need to additionally appoint a special proxy (PPS-1). However, if you already have more than one proxy with the same scope of authority – that is, a general and a special proxy in the same matter – you should designate one of them as the proxy for service of documents.
Deadline
You can submit the application at the earliest in the month following the month in which you started using the online cash register. The right to the refund does not expire – you can do this at any time.
How much will you pay?
The service is free of charge.
How long will you wait?
Businesses that deduct the reimbursement for the purchase of an online cash register can:
- not pay tax for the settlement period – if the tax is lower than or equal to the amount of the relief due for the purchase of the online cash register,
- reduce the tax by the amount of the relief due for the purchase of the online cash register – if the tax is higher than the amount of the purchase relief.
Businesses exempt from the obligation to settle VAT will receive the refund within 25 days of submitting the application to the head of the tax office. The money will be transferred to the bank account specified in the application.
Worth knowing?
Did you know that you must return the money if:
- within 3 years from the date you began keeping records, you stop using the online cash register (e.g. you close your business, declare its bankruptcy, or sell the business and the new owner does not sell to individuals);
- you permanently fail, without the consent of the head of the tax office, to ensure a connection enabling data transmission between the fiscal cash register and the Central Cash Register Repository (Centralne Repozytorium Kas);
- you fail to submit the fiscal cash register for a mandatory technical inspection at least once every 2 years (from the date of fiscalization or the last technical inspection).
Source: https://www.biznes.gov.pl/pl/firma/podatki-i-ksiegowosc/chce-korzystac-z-kasy-fiskalnej/proc_1650-zwrot-kosztow-na-zakup-kasy-fiskalnej-on-line
Posted in:
News
Related posts
-
 GreenBottle CUBE8 Bottle and Can Recycling Machines
-
 Billeterka by Novitus — The Ticketing System of the Future for Carriers!Billeterka by Novitus — the ticketing system of the future for carriers!Read more
-
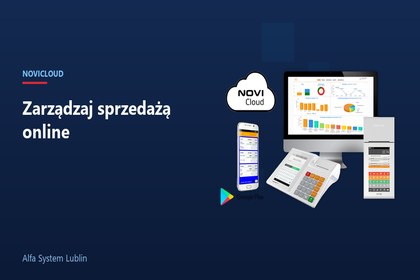 Novitus Fiscal Cash Register Integrated with the NoviCloud SystemRemote sales management with NoviCloud – your business under control at all timesRead more
-
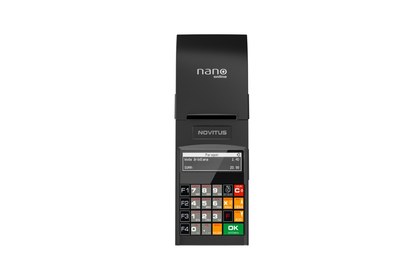 Nano Online Is the Perfect Cash Register for Hair Salons!Nano Online is a cash register that perfectly fits the needs of hair salons, beauty salons, barber shops and SPA studiosRead more
-
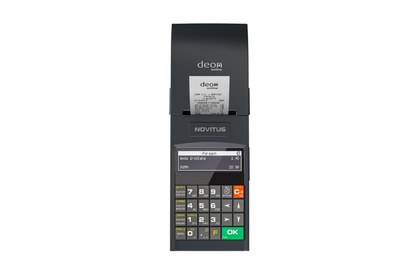 Deon Online in the Online 3.0 SpecificationWe offer the Deon Online version in the Online 3.0 specification.Read more
Add a comment